
COREDO – EU Legal & Compliance Services Expert legal consulting, financial licensing (EMI, PSP, CASP under MiCA), and AML/CFT compliance across the European Union. Headquartered in Prague, we provide seamless regulatory solutions in Germany, Poland, Lithuania, and all 27 EU member states.

Nikita Veremeev
25.12.2023 | 6 min read
Updated: 14.10.2026
In the world of cryptocurrencies and blockchain technologies, the classification of crypto assets defines their characteristics and legal status. It decides which rules apply to a project and which licence it needs. Since 30 December 2024, the EU MiCA Regulation has applied, and it applies directly in the Czech Republic too. In this article, we will explore the widely accepted classification of crypto assets, their regulation at the European Union level and their legal status in the Czech Republic. We will also explain what happened to the Czech VASP licence and which services a Czech CASP licence covers today.
What does Crypto Asset mean?
A crypto asset (token) is a digital representation of value or of a right that can be transferred and stored electronically using distributed ledger technology (DLT) or similar technology.
According to the commonly accepted classification of crypto assets, tokens are differentiated as follows:
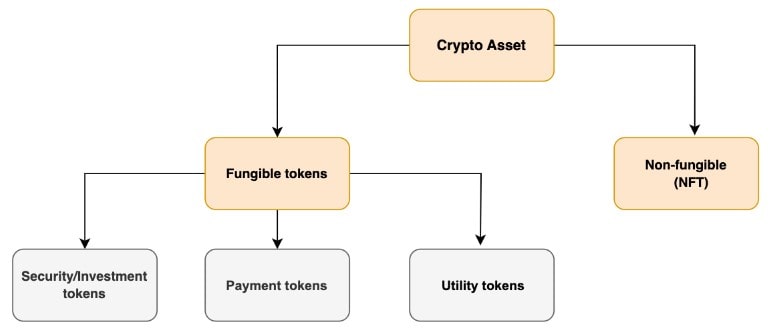
Fungible Tokens are tokens whose units are of equal value and can replace one another. Fungible tokens are typically classified as follows:
- Payment Tokens can serve as a means of exchange or payment;
- Utility Tokens may provide access to a specific product or service;
- Investment Tokens may represent financial claims against the issuer or grant governance rights to their holders (token-holders).
Non-Fungible Tokens (NFTs) are unique tokens that cannot be replaced by other tokens. Such a token is tied to specific information or an asset, such as a music track, video, or image.
How are Crypto Assets regulated at the European Union level?
In the EU, the crypto-sphere is regulated by the MiCA Regulation and the MiFID II Directive. The main aim of MiCA is uniform rules for crypto-assets in the European Union. In contrast, MiFID II focuses on financial instruments and investment services. The MiCA Regulation (Regulation (EU) 2023/1114) was published in the Official Journal of the EU on 9 June 2023 and has applied since 30 December 2024. If a token has the features of a financial instrument, it falls under MiFID II rather than MiCA.
The MiCA Regulation sets standards for identifying and classifying crypto-assets in the European Union. Based on the crypto-assets definition, MiCA differentiates individual tokens into three subcategories: utility tokens, asset-referenced tokens, and electronic money tokens.
- Utility Token (as per MiCA interpretation) is a crypto-asset that is only intended to provide access to a good or a service supplied by its issuer. For a public offer of such tokens, a "White Paper" is drawn up and notified to the competent authority of the home EU member state. No "White Paper" is needed if the good or service already exists or is in operation. The competent authority does not require prior approval of the "White Paper."
- Asset-Referenced Token is a crypto-asset that is not an electronic money token. It aims to maintain a stable value by referencing another value or right, or a combination of them, including one or more official currencies. Such a token may be offered to the public or admitted to trading by an issuer authorised by the competent authority of its EU member state, or by a credit institution. Unlike utility token issuers, issuers of asset-referenced tokens submit their "White Paper" to the competent authority for approval. When the issuer is authorised, its "White Paper" is deemed approved. This requirement protects consumers and market integrity.
- Electronic Money Token - a crypto-asset that aims to maintain a stable value by referencing one official currency. Only an issuer licensed as a credit institution or an electronic money institution (EMI) may offer such a token to the public. The issuer notifies its "White Paper" to the supervisory authority of its EU member state and publishes it. As with the utility token, the competent authority does not require prior approval of the "White Paper."
At the same time, MiCA does not apply to crypto-assets already covered by other EU legislation. Examples are financial instruments (MiFID II), deposits, and funds unless they qualify as electronic money tokens.
An interesting point
Notably, some non-fungible tokens (NFTs) remain outside the scope of MiCA Regulation. The Regulation explicitly states: "This Regulation should not apply to crypto-assets that are unique and not fungible with other crypto-assets, including digital art and collectables."
Nevertheless, MiCA establishes that merely assigning a unique identifier to a token does not make it non-fungible. Tokens issued in large series or collections may be deemed fungible. In that case, MiCA requirements, including the licence, apply to their issuers and providers. At the same time, an NFT may fall under MiFID II if the token has the features of a financial instrument (e.g., representing a tokenized security or tokenized share).
Therefore, a non-fungible token is not automatically free from regulation. We recommend that issuers and providers carefully examine the features and characteristics of each NFT they intend to work with. This way, you will know in advance whether a licence is needed and avoid penalties.
Considering the aspects reflected in the MiCA Regulation and MiFID Directive, the differentiation of crypto-assets can be illustrated as follows:

And what is the situation with the status of a crypto asset in the Czech Republic?
In the Czech Republic, MiCA applies directly, as in all EU countries. National rules were added by Act No. 31/2025 Coll. on the Digitalisation of the Financial Market of 22 January 2025. The Act entered into force on 15 February 2025 and designated the Czech National Bank (ČNB) as the competent authority under MiCA.
The Czech Anti-Money Laundering (AML) Act (No. 253/2008 Coll.) still uses the term "virtual asset", but now defines it through MiCA. A virtual asset is a crypto-asset under MiCA, except crypto-assets under Art. 2(4) MiCA and unique non-fungible crypto-assets that cannot be used for payment or investment.
 A service related to a virtual asset under the AML Act is a crypto-asset service under MiCA, except advice on crypto-assets. A provider of such services remains an obliged person under the AML Act. This is why the MiCA classification also determines your AML obligations.
In a 2023 opinion, the Czech National Bank stated that Czech law does not recognise digital securities, except dematerialised securities held in central or separate records. However, foreign crypto-assets may be (investment) securities under foreign law. Similarly, Czech or foreign crypto assets may be derivatives under Czech and foreign law.
It follows that a token with investment features, such as a security token, may be an investment instrument. MiCA does not apply to such a token. In the Czech Republic, main investment services with such tokens cannot be provided without a ČNB licence under the Capital Market Business Act (No. 256/2004 Coll.), unless the law provides otherwise.
Before MiCA, a Czech VASP licence was sufficient in all other cases. In practice, this was a free trade licence (živnost) for business activity No. 81 "Provision of services related to virtual assets". Since 30 December 2024, new providers cannot operate on this basis: crypto-asset services under MiCA require a CASP licence.
For existing VASPs, the Czech Republic set a transitional period under Art. 143(3) MiCA. A company could keep operating if it provided services under a trade licence before 30 December 2024 and applied for a CASP licence by 31 July 2025. This right lasted until the decision on the application became final, but no longer than 1 July 2026.
The transitional period has now ended. Since 1 July 2026, only companies with a CASP licence from the ČNB or from a regulator of another EU country may provide crypto-asset services in the Czech Republic. Banks, securities dealers and other financial institutions may provide them if they notify their regulator of this (the so-called notification). For operating without a licence, the ČNB may impose fines with an upper limit above CZK 100 million. This is why the Czech VASP licence is history today, not a way to enter the market. How this worked in practice before MiCA is described in our article "How we helped our client launch a cryptocurrency exchange in the Czech Republic?"
Which services does a Czech CASP licence cover?
A CASP licence is granted for one or more of the ten crypto-asset services listed in MiCA. A Czech CASP licence can cover the following services:
- custody and administration of crypto-assets on behalf of clients, as well as transfers of crypto-assets on behalf of clients;
- operation of a trading platform for crypto-assets, exchange of crypto-assets for funds or for other crypto-assets;
- execution, reception and transmission of client orders, placing of crypto-assets, advice and portfolio management on crypto-assets.
A company applies for the licence to the competent authority of its EU country, which in the Czech Republic is the ČNB. A CASP's registered office must be in an EU country where it provides at least part of its services. Its place of effective management must also be in the EU, and at least one director must be resident in the EU.
The minimum capital depends on the class of services: EUR 50,000 for class 1, EUR 125,000 for class 2 and EUR 150,000 for class 3. Class 2 includes custody and exchange, and class 3 covers operating a trading platform. If one quarter of the previous year's fixed overheads is higher than this amount, that higher amount applies.
A CASP licence is valid throughout the EU. To operate in another EU country, a CASP notifies the ČNB, and no physical presence in that country is required. Banks and investment firms do not need a separate CASP licence: they provide crypto-asset services after notifying their regulator. Investment firms do so within the scope of their licence, and electronic money institutions only for custody and transfers of the e-money tokens they issue.
Thus, European legislators have consistently filled the gaps in the legal status of crypto assets and related activities.
The Czech Republic is keeping pace with overall European trends and is systematically and flexibly introducing new norms to regulate the cryptocurrency industry. This creates a favourable landscape for individuals wishing to engage in crypto activities within the Republic.
However, Czech legislation, like that of other jurisdictions, has its own nuances in applying MiCA. In such intricacies, the company COREDO can assist you. How the licensing works is described on our page Crypto Licence in the Czech Republic. Understanding the classification of crypto assets and their regulation is crucial for successful business operations in the Czech Republic and the European Union as a whole.
By Dmitry Vyalkov, LLM, lawyer at COREDO
--------------
1 Please be advised that for the purposes of this article, the terms "crypto asset" and "token" are used synonymously.
2 Point 5 § 1 art. 3 of REGULATION (EU) 2023/1114 OF THE EUROPEAN PARLIAMENT AND OF THE COUNCIL of 31 May 2023 on markets in crypto-assets, and amending Regulations (EU) No 1093/2010 and (EU) No 1095/2010 and Directives 2013/36/EU and (EU) 2019/1937 (hereinafter - “MiCA Regulation”). Date of access: 14.10.2026.
3 Directive on Markets in Financial Instruments repealing Directive 2004/39/EC and amending Directive 2011/61/EU and Directive 2002/92/EC (MiFID II). Date of access: 30.11.2023
4 Art. 2(3) and recitals 10 and 11 of the MiCA Regulation
5 Points 8 and 9 § 4 of Zákon č. 253/2008 Sb. o některých opatřeních proti legalizaci výnosů z trestné činnosti a financování terorismu. Date of access: 14.10.2026
6 Zákon č. 31/2025 Sb. o digitalizaci finančního trhu, § 9 and § 26. Date of access: 14.10.2026
7 Zákon č. 256/2004 Sb. o podnikání na kapitálovém trhu, § 4a. Date of access: 14.10.2026
8 Upozornění České národní banky: Konec přechodného období podle nařízení MiCA k 1. 7. 2026. Date of access: 14.10.2026
9 ČNB: K možnosti investičních fondů investovat do kryptoaktiv. Date of access: 14.10.2026